Showing posts with label Fiscal. Show all posts

Sunday, September 18, 2011

It hurts some times

IMF on fiscal contractions;
Second, external adjustment is not driven solely by the fall in domestic demand from fiscal consolidation. The contractionary effect of fiscal consolidation is now well established, with consequent effects on import demand, and this is something policymakers cannot ignore—fiscal consolidation hurts. But the current account also improves because exports get a boost from the real exchange rate depreciation that tends to accompany fiscal consolidation.

Chapter 4 of WEO- The Twin Budget and Trade Balances

How do changes in taxes and government spending affect an economy’s external balance? Based on a historical analysis of documented fiscal policy changes and on model simulations, this chapter finds that the current account responds substantially to fiscal policy—a fiscal consolidation of 1 percent of GDP typically improves an economy’s current account balance by over a half percent of GDP. This comes about not only through lower imports due to a decline in domestic demand but also from a rise in exports due to a weakening currency. When the nominal exchange rate is fixed or the scope for monetary stimulus is limited, the current account adjusts by as much, but the adjustment is more painful: economic activity contracts more and the real exchange rate depreciates through domestic wage and price compression. When economies tighten fiscal policies simultaneously, what matters for the current account is how much an economy consolidates relative to others. Looking ahead, the differing magnitudes of fiscal adjustment plans across the world will help lower imbalances within the euro area and reduce emerging Asia’s external surpluses. The relative lack of permanent consolidation measures in the United States suggests that fiscal policy will contribute little to lessening the U.S. external deficit.
We find that fiscal policy has a substantial and long-lasting effect on the current account. A fiscal consolidation of 1 percent of GDP improves the current account by over a half percent of GDP within two years, with the improvement persisting into the medium term. The improvement in the current account comes not only through lower imports due to falling domestic demand, but also from an increase in exports arising from a weaker domestic currency.
See chapter 4

Saturday, September 3, 2011

When Fiscal Adjustment is not enough


The mission and the authorities agreed that fiscal adjustment alone will not
ensure debt sustainability (MEFP, paragraph 10). It was recognized that attempts to achieve higher primary fiscal targets over the medium term would not be sustainable unless accompanied by a meaningful reduction in the public debt service burden, which will require burden sharing by all stakeholders. In this context, the authorities have retained debt and legal advisors, publicly announced to seek a comprehensive and substantive restructuring of the public debt, initiated discussions with creditors, and obtained financing assurances from the Paris Club. The authorities’ strategy (Box 4), developed with the assistance of their debt advisors, emphasizes dialogue with all creditors and information transparency (including publishing relevant information on the debt restructuring on their website).
- St. Kitts and Nevis: 2011 Article IV Consultation and Request for Stand-By Arrangement - Staff Report

Saturday, August 27, 2011

Doing Economic Theory in Practice

A book that Olivier Blanchard wishes he had written should be a must read for economic policy students;

To give a sense of what they do, I shall take one example, the creation or reform of fiscal frameworks like the European Stability and Growth Pact (SGP). To come to an intelligent set of recommendations, think of all the elements you need to put together:

•You need to understand what sustainability means in theory and in practice, what the costs of not abiding by it are, and how to assess it. When does a debt-to-GDP ratio become truly excessive? What happens then? How fast can you reach that threshold? How fast can you move away from it?
•You need to understand the long-term effects of deficits and debt on output and its composition. How do deficits and debt affect output in the medium and the long run? How do they affect the interest rate, the net foreign debt position, the capital stock? What is the cost in terms of lost consumption in the future? Which generations gain, which generations lose?
•You need to understand the short-term effects of deficits, and how counter-cyclical fiscal policy can help in the short run. Do deficits affect activity in the same way, whether they come from tax cuts or spending increases? How important are expectation effects? Can the anticipation of large deficits in the future lead to a decrease in consumption and investment, and a decrease in output today? When is this more likely to happen?
•You need to understand the macroeconomic costs of decreased policy flexibility. Are constraints on deficits and debt consistent with an appropriate response of fiscal policy to shocks? What explains sustained divergences within the euro area during the first ten years? Were such divergences avoidable? Then you should determine whether and to what extent fiscal policy is the right tool to deal with country-specific shocks and to what extent it can (should) substitute for the lack of an independent monetary policy. Finally, you need to figure out how much policy space is left to governments after they have fought the great recession and rescued their banks.
•You need to think about how to define the rules in practice. How should debt be defined? How should implicit liabilities, coming from social security and other promises to future generations, be treated? If rules are defined in terms of deficits and debt, what are the most appropriate definitions of the two concepts for the question at hand? How should rules deal with privatization revenues? Should rules apply to gross debt or to net debt? Should the budget be separated between a current account and a capital account? Should the deficit rules apply only to the government current account? Can rules be enforced by politicians or do we need to set up independent committees?
•You need to think about political economy issues. Why are rules needed in the first place? To protect people from their governments, or to protect the governments from themselves? How can a particular set of rules be manipulated or distorted by a national government? How will sanctions against a misbehaving government be imposed? Will these sanctions be credible ex ante? Is international coordination, such as in the G-20 framework, an asset or a diversion from every government’s duties?

To answer these questions, you need many conceptual tools. Among them: a dynamic general equilibrium model with overlapping generations; a model of short-run fluctuations with careful treatment of expectations; political economy models to think about the case for rules; agency models to help you think about the design of specific rules. In each case, with the guidance of theory, you need to look at the evidence, so as to get a sense of which theoretical arguments are more relevant. This is not easy to do. Courses will typically give you the theoretical tools, without much motivation, and let you use them on your own, without much practical training. This is not what this book does. It motivates the use of the tools, gives you the tools, and shows you how they can be used.

FRL in Mongolia - some of the Ceilings

Mongolia's FRL appears interesting;
  1. The floor of structural balance is the deficit of 2 percent of GDP. The structural balance is calculated by using the moving average price of major minerals—currently copper and coal—over 16 years (past 12 years, current year, and future three years). This provision takes effect in 2013.
  2. The ceiling of expenditure growth is the non-mineral GDP growth rate, determined as the greater between its 12-year moving average value and the budget year’s GDP growth rate. This provision takes effect in 2013.
  3. Net present value of public debt cannot exceed 40 percent of GDP. This excludes any borrowing in which the government has agreed to contribute into the paid-in capital of a foreign invested mining entity and which is repayable from the future profits of the entity. The provision takes effect from 2014, with a transition period specified for the preceding years.

IMF's view on Mongolia's fiscal framework;

Medium-term fiscal framework. A sound fiscal policy is necessary for ensuring that Mongolia’s mineral wealth leads to lasting prosperity for all Mongolians. In practical terms, this means managing public spending growth in a way that (i) helps smooth economic growth (through a counter-cyclical fiscal policy); (ii) leaves room for the private sector to thrive; and (iii) provides buffers to insulate the budget—and the economy—against a downturn in global commodity prices. The adoption of the Fiscal Responsibility Law last year was a landmark achievement in this regard. However, the 2011 budget is a big step backwards. The Fiscal Responsibility Law will succeed only if it is strictly adhered to in letter and spirit; failure to do so will undermine its credibility and limits its effectiveness in preventing a recurrence of the policy driven, boom-bust cycles that Mongolia has experienced in the past. Compliance will entail expenditure restraint in the coming years, for example, by keeping spending
roughly frozen in real terms in order to reach the 2013 structural deficit target. Moreover, it is equally important not to circumvent the law by using off-budget vehicles or government guarantees that would, in effect, undo the economic benefits of adhering to the law and come
with the additional costs of an increase in fiscal risks and a loss of transparency. The Development Bank, public-private partnerships, and public guarantees are sources of such quasi-fiscal risk and, if such operations are to proceed, need to be managed prudently and in line with international good practices.

Related;
Strengthening the MTEF Process in Mongolia

Mongolians can learn from the Dutch

The story of the Netherlands is of relevance to Mongolia. How does a democracy with good institutions deal with the sudden discovery of mineral wealth? Initially, the Dutch followed a path which would later become known as the Dutch Disease: a strongly appreciating currency made the non-mineral sector uncompetitive, further aggravated by highly inflationary and unproductive government spending on wages and social transfers. Undoing the negative effects of the wage spiral and the overly generous social welfare system was painful and took more than a decade. The cure for the Dutch Disease was based on a voluntary, negotiated agreement between the same stakeholders which had been responsible for the Dutch Disease—government, labor and business. It was centered on conservative fiscal policies, including low public debt, and wage restraint. The essence of this agreement formed the basis of the subsequently highly successful Polder Model—a framework which also held up very well during the 2008 global financial crisis.

Mongolia has laid a strong legal foundation for a similar macroeconomic and fiscal framework in the three rules which form the basis of the Fiscal Stability Law passed with overwhelming majority in parliament in June 2010. The three rules put strict limits and ceilings on the fiscal deficit, expenditure increases and public debt. However, the essence of the FSL only kicks in 2013, when a structural fiscal deficit of no more than 2 percent of GDP needs to be adhered to. In the transition period, Mongolia would do well to heed the lessons from Holland: curing the Dutch Disease can be long and painful. Preventing the Dutch Disease to afflict the economy in the first place would be the wiser path to take, and, if the story of the Polder Model holds true, will also reward the politicians associated with this path.

See the Annex to Mongolia Quarterly Economic Update - August 2011

Wednesday, February 9, 2011

Quote of the Day- IMF on Sri Lanka program

Did they meet the targets;

So we think that the target was met, but we can't confirm that, and that is why the government has formally asked the Board to not consider that criterion in deciding on this review. It's essentially like a technicality.

Wednesday, September 22, 2010

El Salavador's Eternal Binding Constraints

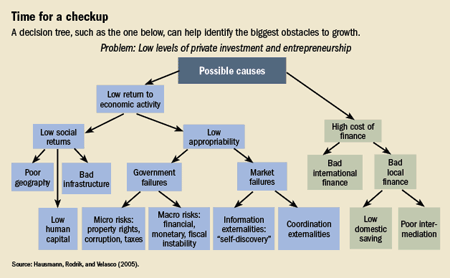
Perhaps the most telling indicator that El Salvador is not constrained by a lack of savings is that a dramatic boost in remittances has not been converted into investment. This suggests that the country invests little, not because it cannot mobilize resources (though savings are low) but because it cannot find productive investments.

IMF latest review of El Salvardor economy;

Over the longer term, further strengthening the economy’s growth prospects and reducing poverty, while safeguarding fiscal sustainability, requires a comprehensive strategy, including measures to raise revenues, structural reforms aimed at enhancing the business climate, and higher private investment...

The authorities’ strategy for 2011, which includes strengthening tax administration to increase revenues as well as reforming energy subsidies, will create space for high-priority social spending and public investment while lowering the fiscal deficit to 3.5 percent of GDP.

“Beyond 2011, timely enactment of a fiscal pact, which includes measures to raise revenue on a durable basis, and continued adherence to expenditure targets in the authorities’ program will be critical to sustain fiscal consolidation, placing the debt-to-GDP ratio on a firm downward path.

“Continued commitment to the dollarization regime has been the cornerstone of macroeconomic and financial stability. While the Salvadoran banking system is liquid and well-capitalized, it would benefit from further reforms aimed at enhancing its resilience. Approving the Financial Sector Supervision and Regulation Law, bolstering the corporate governance of banks, and upgrading the bank resolution framework will be key to this objective. Limiting the fiscal risks associated with the provision of credit by public banks will also be necessary,” Mr. Shinohara said.

Friday, September 17, 2010

Cyprus Economy Watch

IMF releases Article IV review of Cyprus;
Background. Economic conditions have stabilized, and the economy is projected to bottom out in 2010, giving way to a mild recovery in 2011 followed by stronger growth. However, global financial risks remain elevated and muted growth prospects in trading partners weigh on the outlook. The government has taken steps to stabilize the fiscal deficit, but further measures will be needed to reach the official deficit target for 2012 of 3 percent of GDP.

Challenges and staff views. The foremost policy challenge is to achieve the official fiscal consolidation targets so as to put debt ratios on a declining path and provide more space to guard against risks to the financial sector. Further old-age pension reform is also essential. Preserving financial sector stability through early detection of risks remains a top priority in light of the difficult economic and financial environment, and the supervision of cooperative credit societies needs to be strengthened as a matter of urgency. Structural reforms are needed to preserve competitiveness and enhance medium-term growth.

Authorities’ views. The government largely shared the staff’s assessment, while projecting growth to turn positive as soon as 2010 and being more confident that the fiscal targets can be met through general spending restraint and with less focus on the public payroll. The Central Bank of Cyprus (CBC) expressed confidence in the ability of banks to withstand pressures, and this is supported by stress test results. Moving to a single independent supervisor for all credit institutions—a much desirable objective—is not on the political
agenda, but strengthening the supervision of cooperative credit societies seems feasible.

Monday, July 12, 2010

Lithuania's Adjustment

Lithuanian economy - IMF verdict;

Average gross earnings have fallen by 12.4 percent from pre-crisis peaks, but in sectors such as construction and real estate services, labor costs are down 20–25 percent. Unemployment had reached 18.1 percent by end Q1 2010, with high levels of youth and long-term unemployment an increasing concern....

Restoring fiscal sustainability and ensuring financial stability are the
authorities’ key economic objectives
. This supports the long standing currency board arrangement (CBA) and conditions for successful Euro adoption. The latter, would allow an orderly exit from the CBA, eliminate currency risks and reduce liquidity risk, a consideration
given the high degree of euroization (over 70 percent of bank assets but just one-third of deposits). Realizing the ambitious 2014 timeline for euro adoption will require addressing three key challenges: putting the public finances back on a sustainable footing, safeguarding
the health of the financial system, and rebalancing the economy towards tradables to fostermore balanced growth and job creation.

Related:
From Lithuania, a View of Austerity’s Costs
Burden-sharing in Lithuania

Bad Journalism At The Economist

Wednesday, March 25, 2009

Media on Macroeconomic Management

In Ten Trillion and Counting, FRONTLINE traces the politics behind this mounting debt and investigates what some say is a looming crisis that makes the current financial situation pale in comparison.


The other documentary that came out last year

I.O.U.S.A.

Thursday, January 8, 2009

The Basics of Macroeconomic Accounts


The System of Macroeconomic Accounts Statistics: An Overview
Summary: Designed to meet the basic needs of economists and statisticians, this pamphlet is unique in providing an explanation of the key principles underlying macroeconomic statistics when viewed as an integrated system. It highlights the interrelationships between the various sectors and provides a bridge linking the various macroeconomic accounts statistics-national accounts, balance of payments, government finance statistics, and monetary and financial statistics-to assist the reader in understanding the main concepts underlying these statistics. It does so by simplifying many of the concepts, explaining common features and differences, showing how the four key statistical areas harmonize, and providing examples to demonstrate the practical application and uses of the concepts within the conceptual framework. The pamphlet completely updates Pamphlet No. 29, Macroeconomic Accounts: An Overview, by Poul Hølst-Madsen, which was published in 1985.